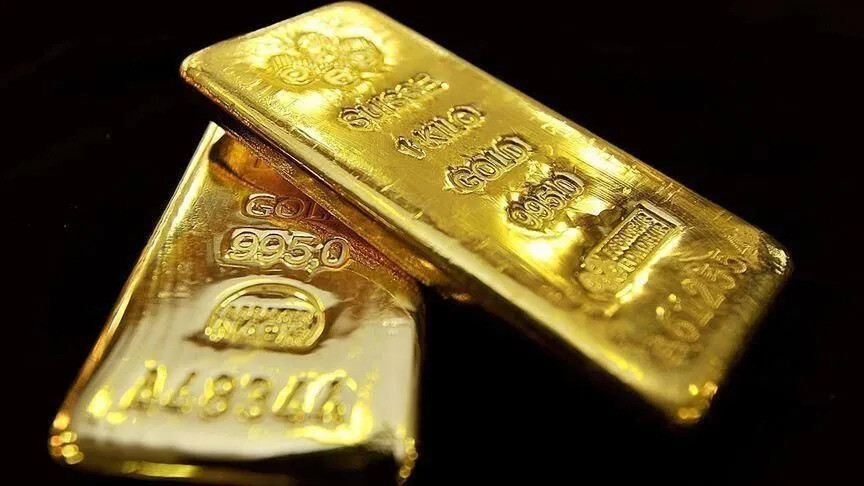
Gold prices fell on Friday by more than 0.4 percent to $4,028 per ounce, influenced by rising oil prices and inflation concerns, as it heads to record its biggest weekly loss in 4 months.
By 09:30 GMT, the price of gold in spot transactions had declined by more than 0.4 percent to $4,028 per ounce. The decline in the yellow metal, considered a safe-haven asset, comes amid volatility in global markets due to tensions in the Middle East and rising oil prices, along with concerns about the impact of energy costs on inflation rates.
Investors are also awaiting the US Federal Reserve's decisions on monetary policy during its meeting on October 27 and 28. Gold has lost about 3.4 percent of its value since the beginning of the week and is heading to record its biggest weekly loss in 4 months.
In other precious metals, silver fell 1.4 percent in spot transactions to $54.6 per ounce, while platinum dropped 0.5 percent to $1,570 per ounce. Global markets are experiencing volatility with escalating military tensions and rising oil prices, amid fears that increased energy costs could lead to inflationary pressures affecting the course of US monetary policy.
Western reports speak of US and Israeli preparations for a wide attack on Iran, amid uncertainty about its timing, coinciding with the upcoming US midterm congressional elections scheduled for November 3. On February 28 last year, the US and Israel launched a war on Iran, with Tehran responding with attacks on Israel and US sites in regional countries, before reaching a ceasefire in April last year.
The US subsequently launched attacks on sites in Iran, amid stalled negotiations between the two countries, despite signing a memorandum of understanding in mid-June. On July 12 last year, Iran announced the reopening of the Strait of Hormuz, following the resumption of US attacks on the 8th of the same month.
Source: Anadolu Agency
Comments (0)